Starting your own business can be demanding, requiring energy, money, and knowledge.
Many entrepreneurs choose to work with a co-founder to split the workload and use their combined skills.
If you and one or more people set up a company without a complicated structure, you will have a partnership firm, like a tandem bike.
Both people pedal to the same place, work together to climb steep hills, and enjoy the momentum. However, if one person isn’t careful with steering, both can fall off!
Understanding how this structure works legally and financially can help protect your personal wealth and preserve your business relationships. Let’s look at how a partnership firm works.
TL;DR
A partnership firm is a simple business structure where two or more people come together to manage a company.
Partners run the company based mostly on a written agreement called a partnership deed. Business owners can easily set up a partnership firm and comply with its rules.
However, partners have unlimited personal liability when it comes to business’s debts.
In this guide, we will explain how partnership firms work, how to register a partnership firm, the partnership firm tax rate, and how to safely dissolve a partnership firm.
The Big Picture: Understanding The Partnership Firm Structure
Two or more people form an unincorporated business called a partnership firm. These partners agree to run a legal business together and share the profits.
In India, the Indian Partnership Act, 1932 governs these businesses. Unlike a private limited company, a partnership firm does not have a separate legal entity.
You and your partners are the same as the business in the eyes of the law. Profits the company makes will therefore belong to you, and debts the company owes will fall on you.
Core Legal Characteristics Of A Partnership
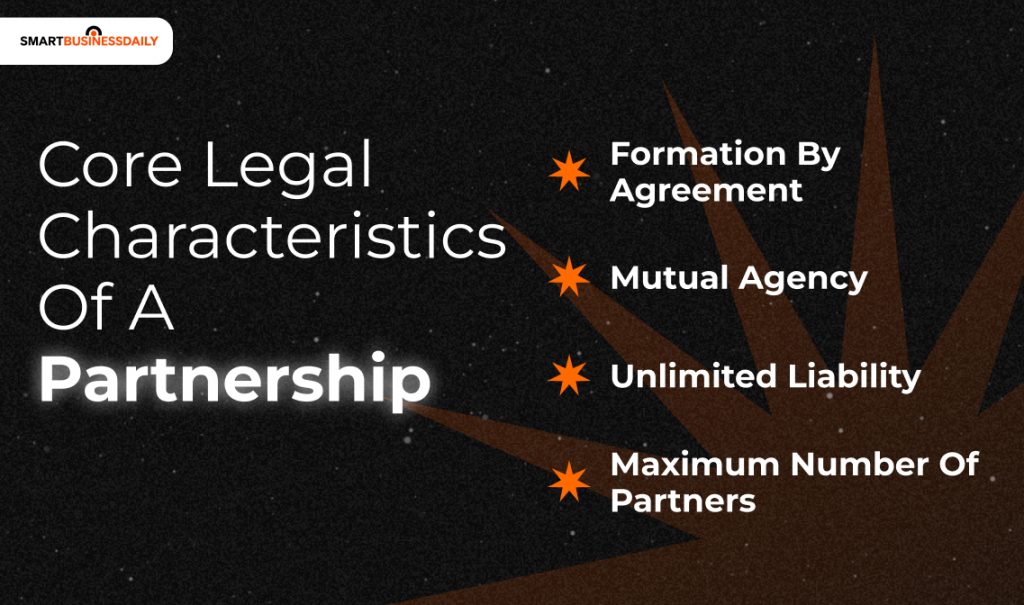
All successful partnerships have certain key principles in place. Before signing any documents, you should understand these rules.
1. Formation By Agreement
A business partnership forms only through an agreement between individuals.
Having a family business or shared property with family members does not automatically create a business partnership. You must all agree to work together within a commercial enterprise.
2. Mutual Agency
This is the most important legal principle. All partners are principals and agents of each other.
This means that any contracts or financial commitments signed by one partner affect all partners in the business.
3. Unlimited Liability
As the business is not a separate legal entity, all partners have unlimited liability. If your business has huge debts or loses a court case, then your personal assets such as savings, cars or property can be claimed by your creditors.
With unlimited liability, creditors can claim from one of your wealthy partners for the full amount of debt owed.
4. Maximum Number Of Partners
While you need at least two people to form a partnership, law sets a maximum number.
Currently, under company law, you cannot have more than 50 partners in a standard partnership firm. If you have more than this, you must change your business into a corporation.
Common Types Of Partnerships
Not all partnerships run in the same way. You can run two main types of partnership, depending on what you want to achieve from your business.
- Partnership at Will:
There is no set end date or reason for ending the partnership. The business can run indefinitely until any partner formally notifies the others that they wish to leave the firm.
- Particular Partnership:
This partnership is set up by the founders to run for one particular project or set time frame.
For example, two contractors may set up a partnership to build one commercial complex. Once the project is complete, the firm automatically ends.
Different Roles Partners Can Play
The amount of time and money partners contribute to the partnership will vary. However, there are several legal categories of partners.
Active Partner
An active partner manages daily business operations. People sometimes call them managing partners.
Sleeping/Dormant Partner
This person invests capital in the business and shares in the profits. They do not participate in the day-to-day running of the business. However, third parties can still hold them personally liable for any debts the business incurs.
Nominal Partner
This person provides the business with their good name or industry influence but does not invest capital or manage the business.
Moreover, they have no share of the profits but are liable to third parties who place confidence in the business based on their name.
Minor Partner
A person under the age of 18 cannot legally enter a contract to become a partner.
However, existing partners can agree to admit a minor as a partner with no personal liability for losses incurred, but with the right to receive the benefits and profits of the business.
The Foundation: Drafting A Bulletproof Partnership Deed
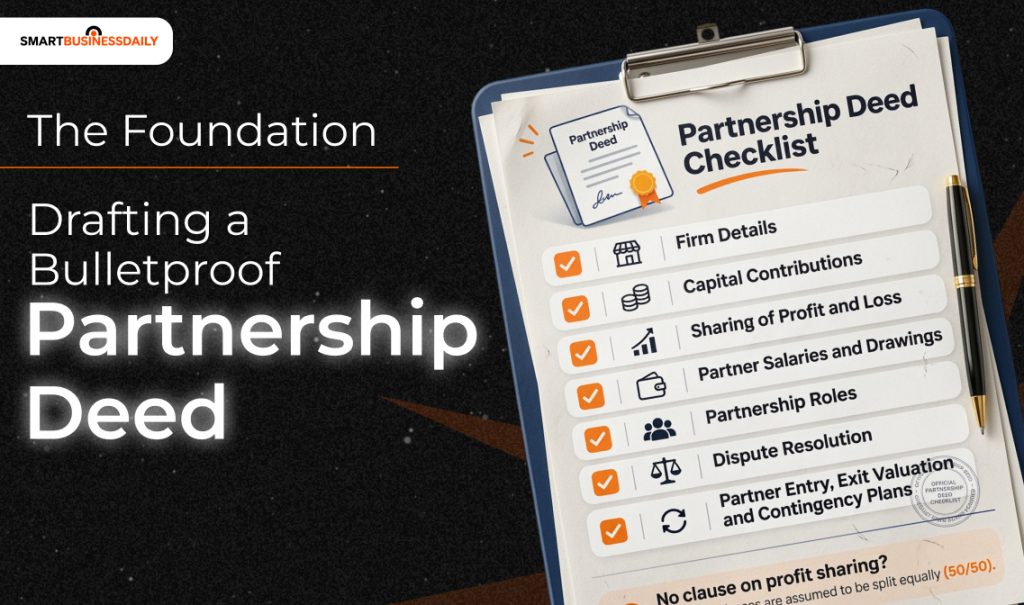
Many new startups begin with a handshake and verbal agreement. However, times can get tough, and memories can fade fast.
A verbal agreement can cause confusion and lead to problems for your business and your friendships.
To avoid any future arguments, you should have a written agreement. This is called a partnership deed.
Moreover, it acts as a constitution for your business. If any arguments arise, you can simply refer back to the deed and follow the agreed solution.
Key Clauses To Include In A Partnership Deed
A detailed partnership agreement will ensure everyone knows what is expected. Your legal advisor should ensure that the agreement includes the following:
- Firm details: The firm’s name and the main office address. What business will be undertaken.
- Capital Contributions: How much cash, equipment, or intellectual property each partner will contribute to the business.
- The Sharing of Profit and Loss: How much profit each partner will receive (in %) and how losses will be shared. If this is not included, it will be automatically assumed that all profits and losses will be split equally (50/50).
- Partner Salaries and Drawings: Will active partners receive a monthly salary or interest on their capital investment? How much can partners take out?
- Partnership Roles: Who will manage day-to-day operations, who will approve large expenditures, and which decisions require unanimous agreement?
- Dispute Resolution: This will ensure that if any deadlocks occur, there is a process in place, such as private mediation or arbitration, to resolve the issue quickly without incurring unnecessary legal costs.
- Partner Entry, Exit Valuation & Contingency Plans: How new partners will be introduced, how a departing partner will be valued, and what will happen if a co-founder dies suddenly or becomes insolvent.
Step-By-Step Guide To Partnership Firm Registration
Under the Indian Partnership Act, partnership firms are not required to be registered.
However, they can begin operations, open bank accounts and deliver services with just an unregistered partnership deed. However, it leaves you open to some serious legal issues.
Why You Should Register Your Partnership Firm
Section 69 of the Partnership Act outlines the serious consequences of not registering your partnership firm.
An unregistered partnership firm will not be able to take legal action against customers/vendors to enforce contractual obligations.
Furthermore, you will not be able to take legal action against other partners in the case of theft of company funds or breach of the partnership agreement.
However, registering your partnership firm will give you full legal rights to defend your rights in court and give you instant credibility with banks and corporate clients.
How To Register Your Partnership Firm
Registering your firm is a simple process. Here is how you can register your firm with your state’s Registrar of Firms:
- Pick A Unique Business Name
Pick a business name for your company that does not infringe any trademarks and does not suggest government endorsement.
- Draft & Sign Partnership Deed
Draft your partnership deed with all necessary clauses. Print the partnership deed on legal stamp paper for the value specified in your state’s Stamp Act. All partners must sign all pages of the agreement in front of 2 witnesses.
- Apply For PAN Card For Your Firm & Open A Bank Account
Because tax authorities treat partnership firms as individual taxable entities, apply for a Permanent Account Number (PAN) in your firm’s name. Once you have your PAN card, you can open a current bank account in your firm’s official name.
- Submit Registration Application (Form 1)
Prepare your registration pack to send to your local Registrar of Firms:
- Completed Form 1 including your firm’s name, main address, length of time, and partner details.
- A copy of your signed partnership deed.
Evidence of your business address (rental agreement, utility bill & property owner’s NOC). Evidence of identity (PAN & Aadhaar) for all partners.
- Pay Fee & Receive Certificate Of Registration
Pay the registration fee outlined by your state government. The Registrar will review your documents and register your firm in the Register of Firms. They will issue you with a Certificate of Registration.
Financial Compliance And The Partnership Firm Tax Rate
Since a partnership firm is considered an extension of the partners under corporate law, it is treated as a separate taxpayer for income tax purposes.
Therefore, you must file separate tax returns for the partnership firm.
Partnership Firm Tax Rate
In order to accurately budget and ensure good cash flow, you should know the direct taxes charged on your business profits:
Basic Income Tax Rate: The government taxes partnership firms at a flat rate. Therefore, these firms pay 30% tax on their net taxable profits.
Surcharge: If the total taxable income of your partnership firm exceeds ₹1 crore in a financial year, then the government charges a 12% surcharge on the income tax amount.
Additional Education and Health Tax Surcharge: The tax authorities charge a mandatory 4% cess on the total of your basic income tax and surcharge.
Tax Deductions
Thankfully, your partnership firm can deduct certain partner payments from the 30% flat tax. This can be done if your partnership deed permits:
Interest on Capital: Your partnership firm can pay interest at a maximum rate of 12% simple interest per annum on capital invested by partners. You can deduct this from your taxable profits.
Salaries & Bonuses: Your partnership firm can deduct the salaries or bonuses paid to active partners.
Profit Distribution: Once your partnership firm pays the 30% flat tax on its net profits, any profit distributed to your partners will be 100% tax-free in their hands.
You Can Also Check: The Ultimate GST Guide: Never Miss A Filing Date Again!
Common Risks And How To Prevent Partnership Disasters
Even close friends may get into conflict under pressure. By identifying common pitfalls and preparing for them, you will be able to put measures in place:
- Unauthorized financial commitments
All partners are agents for each other, so when taking out large loans or paying large checks, ensure your bank requires at least 2 partners to sign the documents.
- Resentment over unequal workloads
Ensure a clear distinction between income from work and income from ownership. Pay active partners an appropriate monthly wage, then divide the remaining profit in proportion to their ownership.
- Confusion over property ownership
Because a partnership firm cannot own real estate, register any property purchased with company funds as jointly owned by all partners.
Additional Resource: What Is A Sole Proprietorship: The Simplest Way To Start A Single-Owner Business.